What the I-645 School-Funding Warning Leaves Out
The ballot says I-645 would decrease funding for schools, universities, and healthcare. It doesn't say when the money would arrive, or what the decrease is measured against.

The ballot says I-645 would decrease funding for schools, universities, and healthcare. It doesn't say when the money would arrive, or what the decrease is measured against.
Washington can make its tax system fairer without accepting every argument for an income tax. A falling spending-to-income ratio is not a needs assessment, and more revenue is not a substitute for budget discipline.
Washington's new income tax has no prior-year estimated-tax safe harbor for first-time filers. A founder or early employee in an exit year can pay the entire tax with a timely filed return and still face a penalty.
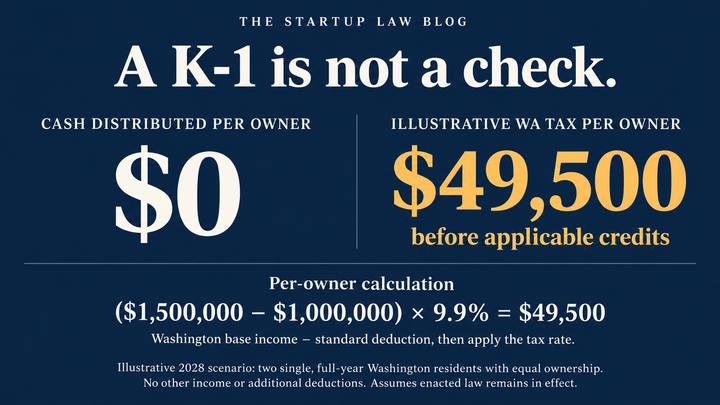
A K-1 is not a check. Starting with 2028 income, Washington’s 9.9% tax can reach profits owners never receive in cash. Here is the two-owner example.
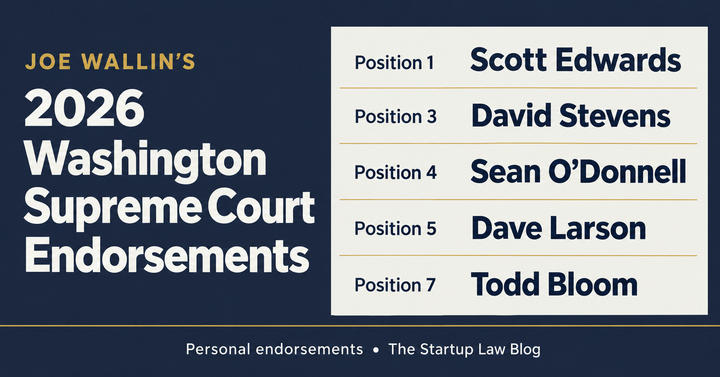
My five Washington Supreme Court endorsements, and the constitutional reasoning, votes, and judicial experience behind them.
S corporation stock is not QSBS. But an S corporation may hold qualifying stock in a new C-corporation subsidiary. Here is how the strategy works—and where it can fail.
A serious M&A term sheet is a tax-planning alarm clock—not a universal tax cutoff. Identify QSBS, gifts, domicile, structure, and §280G issues before the deal gets too far along.
Washington estate tax explained: 2026 exemption changes, 10%–20% rates after July 1, filing deadlines, married couples, and planning for founders.
If you own an S corporation or an LLC taxed as a partnership, your cash distributions don’t determine your tax bill. Retaining profits in the business can leave you with a personal tax obligation—and less cash to pay it.